
Atlantic Coast vs Gulf Coast Which Is Better for Your Vacation Rental

Updated: Aug 28

The "which coast" question is the single most common decision Southeast hosts and buyers face — and vague "both are great" content fails them. Atlantic and Gulf coasts are structurally different products: different water character, different seasonality curves, different storm and insurance profiles, different feeder markets, and different regulatory climates. A host optimizing for summer-family Saturday weeks needs a different coast than one optimizing for winter snowbird income or drive-to volume from Atlanta and Birmingham. This pillar is a decision framework — a weighted side-by-side that maps your goals to the right coast, with linked market evidence rather than travel-brochure generalities.
The Five Variables That Decide the Coast
Five variables separate a good coast fit from a bad one, and they compound rather than operate independently. First is the seasonality profile — when does your market actually earn? Summer-concentrated Atlantic beaches (OBX, Grand Strand, Tybee) behave nothing like winter-concentrated Southeast Florida Atlantic, and both differ from the drive-to Gulf with its shoulder-season strength (Emerald Coast, Southwest Florida). Second is water and beach character: the Gulf's calm, warm, emerald water and sugar-white sand sell a different guest experience than the Atlantic's bigger surf, barrier-island dynamics, and marsh-backed estuaries in Coastal Georgia.
Third is storm and insurance risk — both coasts face hurricane exposure, but low-elevation Southeast Florida and Gulf canal geographies carry heavy flood-insurance burdens that materially affect net yield, so this is a financial variable as much as a safety one. Fourth is demand profile and feeders: Atlantic markets split between international fly-to plus snowbird demand in Southeast Florida and summer-family drive traffic in NC/SC/GA, while the Gulf pulls drive-to family demand from the Southeast interior across 6–8 hour feeder markets. Fifth is the regulatory climate, which varies sharply even within a coast — Florida's local patchwork touches both coasts (SB 280 vetoed June 27, 2024), North Carolina's Atlantic beaches enjoy post-Schroeder permissiveness, and Georgia's Atlantic towns run a town-by-town patchwork. None of these five variables should be evaluated in isolation; the right coast is the one where all five point in the same direction for your product and goals.
Side-by-Side: Atlantic vs. Gulf at a Glance
Variable | Atlantic (NC/SC/GA + SE FL) | Gulf (Emerald + SW FL) |
Peak season | Summer (NC/SC/GA beaches); Winter (SE FL) | Summer + strong shoulder |
Typical ADR tier | $251–$564 (wide range by market) | $300–$500+ (Destin/30A ~$416) |
Occupancy pattern | Peaky summer or winter | ~60% on drive-to markets |
Feeder profile | Drive (VA/MD, NC/SC, GA) + fly (SE FL) | Drive (6–8 hr interior SE) |
Water character | Surf, barrier islands, marsh | Calm, emerald, sugar sand |
Regulation | NC permissive; SC/GA/FL patchwork | FL local patchwork |
Insurance/flood | Coastal flood zones both; SE FL canal-heavy | Gulf canal/low-elevation burden |
Seasonality: The Defining Split
Summer-concentrated Atlantic beach markets show the sharpest seasonality curve on the coast. Outer Banks and Grand Strand markets concentrate roughly 55–65% of annual revenue in June–August. Corolla's August-to-January revenue ratio runs roughly 30:1 on the monthly series, Myrtle Beach July revenue runs more than 10× January, and Tybee peaks in July at $10,401 monthly revenue vs. $2,933 in January — a 3.5× ratio on AirROI. These markets demand three-season merchandising — fall festivals, spring family weeks, heated-pool shoulder — or hosts bleed eight months. Winter-concentrated Southeast Florida Atlantic runs the opposite curve entirely: Miami, Fort Lauderdale, Palm Beaches, and the Keys peak December–March, with Miami Beach hitting $8,038 monthly revenue in its March peak against a September trough of $2,899 on AirROI, and Key West peaking at $17,740 in March against August–October lows near $5,758.
Snowbird monthly blocks and event compression (Art Basel, boat shows, spring break) drive that winter ADR, and summer softness on some Atlantic segments is real — not every Florida Atlantic market peaks in summer. Gulf drive-to markets sit in between: Emerald Coast markets like Destin and 30A run approximately $416 ADR and ~60% occupancy on AirROI with AirDNA market scores in the low-80s, and shoulder-season strength from remote workers and fall/spring family drive trips distinguishes the Gulf from pure summer-peak Atlantic beaches, while Southwest Florida (Naples, Marco, Fort Myers Beach) mixes snowbird winter with Gulf summer family — a dual curve closer to Southeast Florida than to OBX. A handful of dual-engine exceptions defy any single curve and shouldn't be averaged into "Atlantic seasonality": Coastal Georgia splits between a March Savannah peak (St. Patrick's) and a July beach peak, and Tampa Bay peaks January–April (Gasparilla, conventions) with a shallower summer trough than the Pinellas beaches.
Water, Beach, and Guest Experience
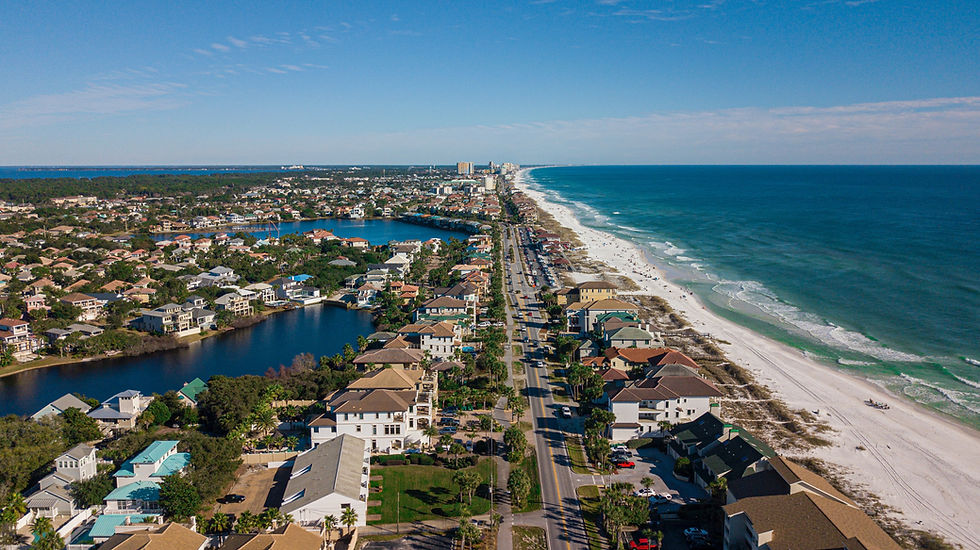
Guest expectations diverge as sharply as the seasonality curves, and mismatching product to coast is where reviews go wrong. Gulf Coast product means calm, warm water, sugar-white sand, a gradual shelf, and family-friendly swimming — the Emerald Coast branding of Destin, 30A, and Panama City Beach sells "emerald water" and pool-home luxury, and guests show up expecting drive-to family time, a pool, boating, fishing, and relaxed swimming. Atlantic Coast product on the NC/SC/GA beaches looks and feels different: bigger surf, barrier-island dynamics, wild horses in Corolla, kiteboarding wind on Hatteras, and marsh-and-estuary ecology in Coastal Georgia, with guests expecting oceanfront Saturday-to-Saturday family weeks, multi-gen reunions, surf and fishing, and maritime forest (OBX, Bald Head). Southeast Florida Atlantic is a third guest experience entirely — condo-heavy in Miami Beach, canal-front "Venice of America" houses in Fort Lauderdale, and Keys reef and diving — drawing international fly-to travelers who want nightlife, diving, sportfishing, and snowbird warmth. The coast you choose should match the guest experience you can actually deliver: a pool home six miles from Destin beach is Gulf product, an oceanfront OBX house with a heated pool is Atlantic family product, and a Brickell high-rise is urban Atlantic — not beach STR in the coastal sense.
Storm, Insurance, and Net Yield
Both coasts face hurricane exposure, so the real question isn't whether a storm risk exists but how flood insurance and elevation eat into net yield after revenue. Southeast Florida Atlantic's low-elevation canal geographies in Fort Lauderdale, Hollywood, and the Keys carry heavy flood-insurance burdens — Key West and Marathon's whole-home inventory sits largely on canals, so verifying the elevation certificate and annual insurance cost before underwriting ADR is essential. Gulf Coast canal and low-elevation properties face nearly identical dynamics: Southwest Florida canal-front homes and Panhandle low-elevation zones carry similar flood-insurance exposure, and net yield calculations must subtract insurance premium growth that followed the 2022 market contraction. Atlantic barrier islands like OBX and Grand Strand present a different profile — oceanfront elevation varies, nourishment projects affect long-term beach access (e.g., the Buxton/Avon 2026 nourishment), and while wind and surge exposure are real, the flood profile differs from that of canal-backed Southeast Florida. Coastal Georgia's marsh geography adds yet another variant, with high tidal range (6–9 feet) and marsh-backed properties carrying a different risk profile than open-ocean OBX frontage. The bottom line: insurance is not a footnote; it is a cost-selection variable in its own right — a $50,000 gross rental with $12,000 in annual insurance behaves completely differently from the same gross figure paired with only $4,000 in insurance.
Demand Drivers and Feeder Markets
Where your guests actually drive or fly from should shape both your coast choice and your marketing copy. Atlantic NC/SC/GA runs on drive-market summer family demand: OBX draws roughly 40% of arrivals from VA/MD combined, Grand Strand draws NC (~20%), SC (~17%), VA (~13%), OH (~8%), and PA (~7–8%) — overwhelmingly drive-in within 4–10 hours — and Coastal Georgia pulls from Atlanta, Charlotte, Ohio, Pennsylvania, and Tennessee. That feeder profile means marketing has to target drive-market planners with Saturday-to-Saturday copy, 60–95-day lead times, and repeat-booking loops. Atlantic Southeast Florida runs on a completely different engine — fly-to plus snowbird demand — with Miami-Dade drawing 28M+ visitors in 2024 and international visitors up +4% YoY, led by Colombia, Brazil, and the UK, while a domestic snowbird drive market fills in the winter; marketing here needs to address international payment complexity, condo legal zones (Miami Beach), and winter event calendars. The Gulf runs on drive-to volume from the interior Southeast: Emerald Coast draws families from Atlanta, Birmingham, Nashville, Memphis, and Texas feeders within 6–8 hours, while Southwest Florida draws Midwest and Northeast snowbirds plus Gulf summer family — marketing there should lean on drive times, pool-home amenities, and honest beach-access positioning.
Regulation Climate by Coast
Regulation friction is not really coast-specific — it is town-specific — but a clear pattern still holds across the map. Florida governs both coasts under the same statewide backdrop: SB 280 was vetoed June 27, 2024, and Fla. Stat. § 509 preemption bars outright bans and duration/frequency regulation while still allowing registration and safety rules; within that frame, the Gulf side carries Walton County requirements, Panama City Beach Ordinance 1632, and Pinellas COU rules, while the Atlantic side carries the Miami Beach single-family STR ban, the Keys transient-license cap, the Fort Lauderdale noise regime, and Volusia County rules — town-specific verification is mandatory on both coasts. North Carolina's Atlantic beaches are the most permissive in the region post-Schroeder, with town-by-town zoning, parking, and occupancy standards, but no registration caps or lotteries, and an occupancy tax of 6% in Dare/Currituck, plus a 6.75% NC sales tax. South Carolina's Atlantic coast is more mixed: the Grand Strand overlay protects supply, Charleston stays tight, NMB has permit proposals pending, and a statewide bill (SC S.442). Georgia's Atlantic coast splits similarly — a Savannah ward cap, a friendly Glynn County, ongoing Tybee litigation, and direct licensing through the Jekyll Island Authority. Taken together, Florida's patchwork is the densest of the four states, NC Atlantic is the most permissive post-Schroeder, and GA and SC split between friendly counties and contested cities.
Decision Framework: Match Goals to Coast
Choose Atlantic (NC/SC/GA beaches) if:. This pillar is a decision framework — a weighted side-by-side that maps your goals to the right coast, with linked market evidence rather than travel-brochure generalities. The coast you choose should match the guest experience you can actually deliver: a pool home six miles from Destin beach is Gulf product, an oceanfront OBX house with a heated pool is Atlantic family product, and a Brickell high-rise is urban Atlantic — not beach STR in the coastal sense.
You want summer-family Saturday-to-Saturday weekly economics
Your feeder market is VA/MD, NC/SC, drive families, or Midwest planners
You can merchandise three-season revenue (festivals, shoulder, heated pool)
You value post-Schroeder NC regulatory stability
Your product is large oceanfront multi-gen homes
Choose Atlantic (Southeast Florida) if:. The third is assuming all of Florida is winter-peak, when in fact Southeast Florida Atlantic peaks in winter, the Panhandle Gulf peaks in summer, and First Coast/Northeast Florida blends event and summer curves — "Florida seasonality" is not one curve. Summer-concentrated Atlantic beaches (OBX, Grand Strand, Tybee) behave nothing like winter-concentrated Southeast Florida Atlantic, and both differ from the drive-to Gulf with its shoulder-season strength (Emerald Coast, Southwest Florida).
You want winter snowbird and international fly-to demand
Your product is a condo, a canal-front house, or a Keys whole-home (licensed)
You can navigate dense municipal registration and license scarcity
You accept summer softness on some Atlantic segments
High ADR justifies compliance cost (Key West, Delray, Fort Lauderdale)
Choose Gulf (Emerald/SW FL) if:. The Gulf runs on drive-to volume from the interior Southeast: Emerald Coast draws families from Atlanta, Birmingham, Nashville, Memphis, and Texas feeders within 6–8 hours, while Southwest Florida draws Midwest and Northeast snowbirds plus Gulf summer family — marketing there should lean on drive times, pool-home amenities, and honest beach-access positioning. Gulf evidence posts: Emerald Coast market report, Florida Gulf pillar, Southwest Florida market report.
You want drive-to family volume from interior Southeast feeders
Your product is a pool home, sugar-sand beach access, and boating/fishing
You value shoulder-season strength and ~60% occupancy markets
You can compete in the pool-home amenity arms race
You accept the Florida local patchwork regulation
Choose dual-engine markets (Coastal Georgia, Tampa) if:. Coastal Georgia (Georgia Atlantic) is the archipelago dual-engine market, with Savannah peaking in March around St. A handful of dual-engine exceptions defy any single curve and shouldn't be averaged into "Atlantic seasonality": Coastal Georgia splits between a March Savannah peak (St. We build direct-booking brands, listing-optimization systems, and market-specific content strategies for independent STR operators across the Gulf Coast, Appalachian Mountains, Coastal Georgia, the Carolinas, Virginia, and the Southeast lake country.
You want spring and summer peaks on different products
You can run segmented calendars and email campaigns
You accept more complex merchandising for smoother annual revenue
Deep Dive: Atlantic Coast Market Profiles
Outer Banks (North Carolina Atlantic) is the premium large-home summer-family market: Corolla runs ~$564 ADR with a 95-day lead time, and 8-in-10 repeat visitation, and revenue concentrates 55–65% in June–August. Bigger Atlantic surf, wild horses, maritime forest, and Hatteras kiteboarding define the guest experience, backed by post-Schroeder regulatory stability. The marketing angle is Saturday-to-Saturday booking, festival shoulder, heated-pool October stays, and VA/MD repeat email capture; entry cost for oceanfront sits among the highest on the seaboard, so this market rewards operators who can merchandise three-season revenue. Grand Strand (South Carolina Atlantic) spans the volume-to-premium spectrum: Myrtle Beach runs $251 ADR across 8,400+ listings with real commodity condo risk, while North Myrtle Beach commands $372 ADR on a family-house repeat culture, and golf shoulder sustains the off-season across 18.2 million visitors.
The marketing angle is anti-commodity tower specificity in Myrtle or section identity in North Myrtle, and entry cost is the lowest condo barrier on the Southeast coast — best suited to differentiated volume or premium family operators. Coastal Georgia (Georgia Atlantic) is the archipelago dual-engine market, with Savannah peaking in March around St. Patrick's, Tybee peaking in July at $444 ADR, and St. Simons drawing golf and RSM Classic crowds at $399 ADR, all set against marsh ecology, a mild winter climate, and year-round golf; the marketing angle leans on overflow lodging, eco-tourism shoulder, and snowbird monthly blocks, while regulation includes the Savannah ward cap, Tybee litigation, and a friendly Glynn County, with entry cost lower than OBX oceanfront but below the Keys premium tier.
Southeast Florida Atlantic (Miami through West Palm) is the winter snowbird and international fly-to market: Miami Beach hits $8,038 monthly revenue at its March peak against a $2,899 September trough, Key West runs ~$695 ADR under license-gated scarcity, Fort Lauderdale offers canal-front houses, and Delray posts $52,523 average revenue with +24.4% growth. The marketing angle centers on the winter event calendar, condo legal zones, international payment handling, and licensed Keys inventory, though entry costs and regulatory friction both run highest on this stretch of the coast. First Coast and Space Coast (North/Central Florida Atlantic) round out the Atlantic side with St. Augustine history, Jacksonville Beach, Cape Canaveral rocket launches, and Daytona events; seasonality is mixed — some markets peak summer, others layer event demand — and while ADR runs lower than Southeast Florida's premium tier, regulation friction is also lighter than Miami Beach, making heritage tourism, launch viewing, and cruise-terminal proximity the strongest marketing angles.
Deep Dive: Gulf Coast Market Profiles
Emerald Coast (Florida Panhandle Gulf) is the drive-to family pool-home market, with Destin/30A running ~$416 ADR and ~60% occupancy on an AirDNA market score in the low-80s, sugar-white sand, and emerald calm water drawing feeders from Atlanta, Birmingham, and Nashville within 6–8 hours, plus shoulder strength from remote workers. The marketing angle is pool-home lifestyle, named-subdivision identity, honest drive-time framing, and fall/spring family positioning; regulation is a patchwork of Walton/Okaloosa/Bay County, including PCB Ordinance 1632, and entry cost ranges widely from PCB value to 30A luxury. Southwest Florida Gulf — Naples, Marco Island, Fort Myers Beach, Sanibel, Captiva — blends snowbird winter with Gulf summer family, carries canal-front flood-insurance burden on low-elevation inventory, and commands higher ADR at the premium tier; the marketing angle runs on boating, fishing, shelling, golf, and snowbird monthly stays, with regulation varying by Lee and Collier County and additional Sanibel STR restrictions.
Tampa Bay Gulf (Pinellas/Hillsborough) splits between the Pinellas barrier islands (Clearwater, St. Pete Beach, Treasure Island) and the Tampa urban base camp, with Pinellas carrying a 13.0% combined TDT against Tampa's 13.5%, a Clearwater 31-day residential minimum, a St. Pete Beach three-stays-per-year cap, and Tampa running $219 ADR urban volume against Clearwater's premium beach rates; the marketing angle is honest product separation between urban and beach, with dual seasonality peaking at Tampa's Q1 Gasparilla and the beaches' summer season. Alabama and Mississippi Gulf serve as an adjacent comparison point: Gulf Shores and Orange Beach in Alabama, plus coastal Mississippi markets, compete with the Florida Panhandle for drive-to family demand, often at lower entry cost with a similar product (pool homes, white sand) but a different tax and regulation stack — relevant context for investors weighing the broader Gulf against Atlantic NC/SC.
Acquisition Cost and Cap-Rate Context
Coast selection is partly an acquisition math problem, and the same gross-revenue numbers can support very different purchase prices depending on where you buy. Atlantic oceanfront premium markets like OBX, Corolla, and Duck command top-tier weekly rates but equally top-tier purchase prices, so cap rates compress on oceanfront — underwrite on in-season occupancy (80–90%+ for established oceanfront), not the full-year 38% portfolio average. Gulf pool-home mid-tier product, by contrast, offers strong gross revenue with a somewhat lower oceanfront acquisition premium, especially in inland subdivision product with beach access, where amenity capex like pools and outdoor kitchens becomes part of the investment thesis rather than a side cost. Atlantic volume entry through Myrtle Beach condos offers the lowest acquisition barrier on the coast, though per-listing revenue is thinning with +52% YoY supply growth — entry cost still supports portfolio-scale plays. Southeast Florida scarcity plays — Key West licensed inventory and Miami Beach legal-zone condos — trade that scarcity for regulation friction, and while the ADR ceiling is high, license acquisition may end up being the binding constraint on returns.
Insurance and Net Yield: Worked Example
Consider a simplified net-yield comparison (for directional, not financial, purposes) across three representative properties. An OBX Corolla oceanfront property might run $55,000 gross, $8,525 in Airbnb fees at 100% OTA, $6,000 in insurance, and $8,000 in operating costs — net before debt service. Net varies sharply by acquisition price, and shifting 30% of bookings directly saves roughly $2,558 in platform fees. A Destin pool home might run $50,000 gross with a similar fee structure, potentially lower wind exposure than open-ocean OBX, but flood-zone verification required on low elevation, and shoulder revenue that can add $5,000–$8,000 gross that OBX summer-only hosts simply miss. A Key West licensed condo sits at the top of the range: $96,000 gross, $14,880 in Airbnb fees, $10,000–$15,000 in insurance on a coastal condo, and the highest ADR ceiling of the three, with direct booking at 30% saving roughly $4,464 annually. The pattern that emerges is that net yield after insurance often reverses the gross-ADR ranking — always model insurance, flood zone, and tax stack together rather than comparing gross ADR alone.
Representative Markets: Where to Drill Deeper
Atlantic evidence posts: Outer Banks seasonality playbook, Grand Strand market report, Coastal Georgia pillar, Florida Southeast pillar. Gulf evidence posts: Emerald Coast market report, Florida Gulf pillar, Southwest Florida market report. Gulf drive-to markets sit in between: Emerald Coast markets like Destin and 30A run approximately $416 ADR and ~60% occupancy on AirROI with AirDNA market scores in the low-80s, and shoulder-season strength from remote workers and fall/spring family drive trips distinguishes the Gulf from pure summer-peak Atlantic beaches, while Southwest Florida (Naples, Marco, Fort Myers Beach) mixes snowbird winter with Gulf summer family — a dual curve closer to Southeast Florida than to OBX.
Common Mistakes When Choosing a Coast
Five mistakes account for most of the coast-selection errors hosts make. The first is buying Gulf product but marketing it like an Atlantic product — pool homes marketed as "oceanfront" when beach access is actually a 10-minute drive — producing mismatch reviews, because Gulf guests expect calm swimming and a pool lifestyle, while Atlantic guests expect surf, oceanfront decks, and a weekly Saturday rhythm. The second is ignoring insurance in the ADR comparison: a $500 ADR Keys condo carrying $14,000 in annual flood insurance may net less than a $350 ADR OBX house carrying only $5,000 in wind coverage, so the discipline is to model net, not gross. The third is assuming all of Florida is winter-peak, when in fact Southeast Florida Atlantic peaks in winter, the Panhandle Gulf peaks in summer, and First Coast/Northeast Florida blends event and summer curves — "Florida seasonality" is not one curve. The fourth is underwriting OBX on full-year occupancy: portfolio averages of roughly 38–54% understate the in-season oceanfront performance of 80–90%+, so peak-summer weeks need to be underwritten separately from winter carrying cost. The fifth is entering the Myrtle commodity middle without differentiation — 8,400+ listings competing at $251 ADR punish generic studios, and coast selection alone does not rescue undifferentiated product.
Keep going on Crest & Cove: Destin against AirROI, not leftover year · Myrtle Beach against AirROI $20,946 · the Crest & Cove intro · local SEO keywords that actually book · the five elements of a converting hero · how to compare STR marketing agencies · Asheville paddling spots worth the drive · OBX vs Emerald vs Myrtle against AirROI pins.
Related Reading
Keep reading on same-cluster Crest & Cove pages that stay on labeled local lines without costume-corridor copy.
Florida Atlantic Coast Vacation Rentals for Independent Hosts
Marketing a Short-Term Rental in Florida Atlantic Coast the Complete
DIY vs. Hiring Marketing Help for Inland PA and Mid-Atlantic Hosts
How to Market a Short-Term Rental in Atlantic Beach NC Fort Macon
How to Market a Short-Term Rental in Atlantic Beach Neptune Beach FL
Virginia Mid-Atlantic STR Marketing: Keep the Driveway Honest
PA Mid-Atlantic Inland Bridge: Only Two Towns Are Actually Live
PA and Mid-Atlantic Inland SEO Starts With the House You Run
Regulation Literacy for PA Mid-Atlantic Marketers: Not Legal Advice
Market the Inland PA House You Run, Not a Trophy Corridor Myth
Seasonality Calendars Hosts Should Market in Pa Mid Atlantic Inland
DIY vs. Hire in Many, LA: Why Independent Hosts Still Run Most Listings
DIY or Hire in Depoe Bay: What the Numbers Say for STR hosts
Work with Crest & Cove Creative
Crest & Cove writes AirROI pins, not leftover occupancy. Nationwide. crestcove.co or (256) 998-7502.
We help hosts in the Southeast United States with listing photography and titles optimized for local search intent, event-calendar pricing, guest guidebooks, and direct-booking pages that drive repeat bookings. If you want hands-on help implementing any of that on your property, our team takes a limited number of new engagements per quarter. Reach out at crestcove.co or (256) 998-7502.
Frequently Asked Questions
Is the Gulf Coast or the Atlantic Coast better for vacation rentals?
Neither coast is universally better — the right answer depends entirely on your product and feeder market. The Gulf suits drive-to family pool-home volume with shoulder strength, drawing feeders from Atlanta, Birmingham, Nashville, and Memphis within 6–8 hours and running roughly $416 ADR with ~60% occupancy on markets like Destin/30A. Atlantic NC/SC/GA suits summer-family oceanfront weeks, with markets like OBX Corolla commanding ~$564 ADR and 55–65% of revenue concentrated in June–August. Southeast Florida Atlantic suits winter snowbirds and international demand, peaking December–March, with events like Art Basel and boat shows driving ADR. Match the coast to your product type and the feeder market you can realistically reach, rather than picking.
Which coast has better seasonality?
"Better" seasonality depends on whether you want summer income, winter income, or distributed shoulder revenue, because the three coasts run genuinely different curves. Gulf drive-to markets like Destin/30A show stronger shoulder occupancy at roughly 60%, thanks to remote workers and fall/spring family drive trips, compared with summer-peak Atlantic beaches like OBX and Grand Strand, which concentrate 55–65% of revenue in June–August alone. Southeast Florida Atlantic runs the inverse curve entirely, peaking in winter with Miami Beach hitting $8,038 in monthly revenue in March against a $2,899 September trough. A host chasing the smoothest annual revenue curve should look at the Gulf's shoulder strength; a host who can merchandise three-season demand.
Which coast is riskier for hurricanes and insurance?
Both coasts face real hurricane exposure, so risk comes down to elevation and insurance stack rather than which ocean you're on. Southeast Florida's canal geographies in Fort Lauderdale, Hollywood, and the Keys carry some of the heaviest flood-insurance burdens in the region, and Gulf low-elevation canal homes in Southwest Florida and the Panhandle face similar dynamics. Atlantic barrier islands like OBX carry more wind and surge exposure but a different flood profile than canal-backed Southeast Florida, while Coastal Georgia's marsh geography (6–9 feet of tidal range) adds yet another risk variant. Whichever coast you're considering, verify the elevation certificate and annual premium before purchase — insurance can reverse a gross-ADR.
What are typical ADR differences between the coasts?
ADR varies widely both between and within coasts, so town-specific data matters more than coast-wide averages. Emerald Coast runs roughly $416 ADR on AirROI, while OBX Corolla commands a premium-tier ~$564 against a broader regional average of about $276. Grand Strand spans roughly $251 to $372, depending on the specific town — Myrtle Beach at the lower end, North Myrtle Beach at the higher end — and Key West runs $626–$695 at the top of the range, given its license-gated scarcity. Because these ranges are so wide within a single coast, compare the specific town you're evaluating rather than assuming a coast-level average tells you much.
How does regulation differ by coast?
Regulation is fundamentally a town variable rather than a strict coast variable, though patterns do emerge at the state level. Florida's patchwork is the densest on both of its coasts, even after SB 280 was vetoed, with individual counties and cities like Walton, Panama City Beach, Miami Beach, and the Keys each running their own rules. NC Atlantic is the most permissive in the region post-Schroeder, with no registration caps or lotteries. GA and SC both vary town by town — Savannah's ward cap and Tybee litigation sit alongside a friendly Glynn County, while Charleston runs tight, and the Grand Strand overlay protects supply. Always verify at the specific town.
Should I buy on the Gulf for summer rentals?
Yes — Gulf summer family demand is the core revenue engine for Emerald Coast and Panhandle markets, and it comes with an advantage pure summer-peak Atlantic beaches lack: real shoulder-season depth. Destin/30A already runs at ~60% occupancy, with shoulder strength from remote workers and fall/spring family drive trips, which means the revenue curve is less concentrated in a single quarter than in a market like OBX, where 55–65% of annual revenue lands in June–August alone. If your goal is more consistent occupancy across more months of the year rather than a single peak season, the Gulf's summer-plus-shoulder profile is the stronger structural fit.
Should I buy Atlantic NC for summer rentals?
Yes — if you can merchandise three-season revenue and absorb the 55–65% summer concentration that defines these markets. OBX and Grand Strand are proven summer family markets with strong drive-market repeat visitation, including OBX Corolla's 95-day lead time and an 8-in-10 repeat visitation rate. The tradeoff is that these markets demand active shoulder-season merchandising — fall festivals, spring family weeks, heated-pool October stays — because without it, hosts effectively bleed revenue across eight months of the year. For operators willing to build that shoulder-season strategy, Atlantic NC's summer economics and repeat-guest loyalty are hard to match elsewhere.
Where can I find more in-depth coast-specific guides?
State and regional pillars linked in the Related Reading section below cover NC, SC, GA, VA, Florida Gulf, Florida Atlantic, and Florida Southeast in full depth, each with town-level ADR, seasonality, and regulation detail beyond what this coast-level comparison can cover. The third is assuming all of Florida is winter-peak, when in fact Southeast Florida Atlantic peaks in winter, the Panhandle Gulf peaks in summer, and First Coast/Northeast Florida blends event and summer curves — "Florida seasonality" is not one curve.
About the Authors
Crest & Cove Creative is a nationwide short-term rental marketing agency founded by Thomas Garner and Jacob Mishalanie. We build direct-booking brands, listing-optimization systems, and market-specific content strategies for independent STR operators across the Gulf Coast, Appalachian Mountains, Coastal Georgia, the Carolinas, Virginia, and the Southeast lake country. AirROI — OBX, Grand Strand, Emerald Coast, Coastal Georgia, Southeast Florida market reports, Jun 2025–May 2026.
Explore coast-specific guides across markets we work silo:. Regulation friction is not really coast-specific — it is town-specific — but a clear pattern still holds across the map. Summer-concentrated Atlantic beach markets show the sharpest seasonality curve on the coast. Fourth is demand profile and feeders: Atlantic markets split between international fly-to plus snowbird demand in Southeast Florida and summer-family drive traffic in NC/SC/GA, while the Gulf pulls drive-to family demand from the Southeast interior across 6–8 hour feeder markets.
Sources
AirROI — OBX, Grand Strand, Emerald Coast, Coastal Georgia, Southeast Florida market reports, Jun 2025–May 2026. OBVB — repeat visitation and feeder data. VISIT FLORIDA, GMCVB — Southeast Florida tourism. Florida Governor's Office — SB 280 veto June 27, 2024. Tourism Economics — Dare County revenue. Grand Strand Chamber — visitor spending. FEMA flood zone data. Insurance Information Institute — coastal property insurance trends.


Comments