
Prescott, AZ Short-Term Rental Market Report: What Hosts Earned


Prescott's short-term rental market is small enough to describe precisely and specific enough that its numbers should never be blended with a neighboring metro's file. This report walks through what a current Air ROI extract, covering August 2025 through July 2026, actually shows for the roughly 801 active listings operating in Prescott: typical annual revenue, average daily rate, occupancy, revenue per available room, the year-over-year trend, the seasonal shape of the calendar, and how the market compares to Phoenix on the same dataset window.
None of what follows is a projection, a pitch, or advice about whether to buy, sell, or operate in this market. It is a plain accounting of one extract's numbers, presented so that anyone reading them, whether a host, a buyer, a lender, or a curious neighbor, is working from an accurate baseline rather than a rounded-up guess or a borrowed figure from a bigger city down the highway. Confirming remaining 2026 license and tax status for any specific property still requires a direct check at prescottaz.gov; this report covers market performance, not registration compliance. This is not legal advice.
The report is organized to move from the headline number outward: what listings earned, how that revenue was built from rate and occupancy, which direction the market is trending, what kind of property the sample actually represents, who is booking these stays, and how the calendar's seasonal shape should inform anyone reading these figures for planning purposes.
The Headline Number: What Prescott Listings Earned
On the current extract, typical listings in Prescott earned about $25,061 over the trailing year, drawn from a sample of 801 active rentals. That figure covers the twelve-month window running from August 2025 through July 2026, and it represents the typical, not the top-performing or bottom-performing, listing in that sample. Individual properties will vary above and below this figure depending on size, location, condition, pricing strategy, and management quality, but $25,061 is the number that describes the market as a whole in this sample.
It is worth stating plainly what this figure is not. It is not a projection of what a specific property will earn going forward, and it is not adjusted for any individual host's costs, mortgage, management fees, or local taxes. It is a revenue figure only, describing gross booking income across the sample, and any net-profit conversation needs to start from this baseline and subtract a specific property's own cost structure separately.
How That Revenue Number Gets Built: Rate, Occupancy, and RevPAR
The $25,061 typical annual revenue figure is the product of two underlying numbers working together: an average daily rate of about $220, and an occupancy rate of 40.1 percent. Multiplying rate by occupancy and extending across the year produces a revenue per available room, or RevPAR, of about $86, which is the figure that most directly reflects what a listing earns per available night once both pricing and fill rate are accounted for.
None of these three figures are exceptional in either direction relative to a seasonal mountain-town market. An ADR of $220 is a moderate, not premium, nightly rate. An occupancy rate of 40.1 percent means well under half of available nights are booked across the full year, which reflects a market with real but bounded, seasonal demand rather than a market that fills consistently. RevPAR of $86 is the number that ties those two together, and it is the figure worth focusing on for anyone trying to estimate what a specific property might generate per available night, since ADR alone overstates performance by ignoring the nights that go unbooked.
Reading these three numbers together also clarifies what a host can and cannot influence directly. Rate is within a host's control day to day, subject to what the market will bear. Occupancy responds to a combination of rate, listing quality, marketing, and overall market demand, some of which a host controls and some of which they do not. RevPAR is the resulting outcome, and it is the number a host should track over time as the clearest single indicator of whether pricing and marketing decisions are actually working.
The Trend Line: Revenue Down, Supply Up
Beyond the snapshot figures, the extract shows a year-over-year trend worth taking seriously: revenue is down about 4.5 percent while active supply is up about 16.1 percent over the same period. Read together, those two figures describe a market where new listings have been entering faster than trailing revenue has grown, which puts downward pressure on the average performance per listing even if total market-wide demand has held roughly steady or grown modestly.
This is not evidence that the Prescott market is failing. Markets absorb new supply constantly, and a 16.1 percent supply increase is a meaningful but not extreme figure for a market of this size. What it does mean is that any revenue projection built from this data should lean conservative rather than optimistic, since the most recent trend points toward more competition for a slightly smaller trailing revenue pool, not toward an expanding pie that comfortably supports every new entrant at the same performance level as the existing sample.
It is also worth considering how this trend might evolve. If supply growth continues to outpace revenue growth, average performance per listing could continue softening until either new supply growth slows or overall demand catches up. If supply growth moderates while demand holds steady or grows, the current pressure could ease. this sample cannot forecast which of those paths is more likely; it can only establish that the most recent trailing year shows the former pattern, and that pattern is the one a host should plan around until newer data suggests otherwise.
What Kind of Property This Sample Actually Represents
Entire-home listings make up about 95.1 percent of the Prescott sample behind this sample. That means the $25,061 typical revenue figure, and the $220 ADR, 40.1 percent occupancy, and $86 RevPAR figures alongside it, are most representative of a whole-house short-term rental, not a private room, shared space, or accessory dwelling unit. A smaller unit type operating in this same market is a meaningfully different product, and comping it directly against a sample this heavily weighted toward whole homes will likely overstate what that unit type could realistically earn.
This distinction matters for anyone using this report to evaluate a specific property. A five-bedroom whole-home listing and a one-bedroom accessory unit are not competing for the same guest or the same price point, even though both would technically fall under the same short-term rental category. Anyone narrowing this data down to a specific comp set should filter for product type first, not just location, before drawing conclusions about what a given property should be expected to earn.
Who Is Actually Booking These Stays
The extract identifies the typical Prescott guest as arriving from Phoenix, then Tucson, for a stay of about 4.9 nights, booked roughly 44 days ahead of arrival. That profile describes a planned, short highland getaway rather than a long-stay vacation or a location-independent remote-work booking. About 25.0 percent of listings in the sample currently set a 30-night minimum stay, but that figure describes a hosting choice, not a measurement of guest demand for stays that long, since the typical stay length across the full sample remains under five nights.
Understanding this guest profile matters beyond marketing copy; it also shapes how a host should think about calendar strategy, minimum-stay settings, and even property design decisions like furnishing choices, since a listing built and marketed around a hypothetical extended-stay guest is targeting a segment that this data does not show as a significant share of current demand. A listing built around the actual short-trip, planned-getaway guest is aligning itself with the demand this market is already delivering.
The Seasonal Shape: One Peak, Two Shoulders, Two Distinct Soft Months
August stands out clearly as the market's strongest revenue month in this sample, driven by the same Phoenix-and-Tucson guest pattern described above, with peak bookings typically locking in during the 44-day lead window that would place much of that activity in June and early July. March and December carry meaningful income after the August peak, functioning as genuine shoulder months rather than either peak-level or off-season performance.
The market's softness is not evenly distributed either. February registers as the revenue hole, the weakest month for total revenue across the sample, while July registers separately as the occupancy hole, the month with the lowest share of booked nights. These are distinct problems with potentially distinct causes, and a host or analyst reading this report should not assume a single seasonal discount strategy addresses both months equally well, since a revenue problem and an occupancy problem do not necessarily respond to the same fix.
Taken together, this seasonal shape argues for a four-tier calendar approach rather than a simple peak-versus-off-season model: premium pricing and availability protection during August, moderate shoulder-season pricing for March and December, and a deliberate, diagnosed response to February and July that treats each soft month according to its own specific weakness rather than a blanket discount applied everywhere the calendar looks slow.
Prescott Against Phoenix: Two Files, Not One Blended Market
On the same extract and the same August 2025 through July 2026 window, Phoenix shows typical listings earning about $35,247 across roughly 5,820 active rentals, a considerably larger and higher-earning market by both revenue and listing count. That comparison is useful context, but it should never substitute for Prescott's own figures in any packet, projection, or public-facing material describing a Prescott property.
The two markets differ in more than just scale. Phoenix serves a larger, more urban, more year-round traveler base, including business travel that Prescott's smaller highland market does not draw at the same scale. Prescott's guest, as this report's data shows, is overwhelmingly a short-trip visitor from within the state, planning a highland getaway rather than passing through on unrelated travel. Those structural differences, not just the raw revenue gap, are the reason the two markets need to stay on separate lines in any analysis.
A reviewer evaluating a Prescott property who sees Phoenix's larger number quoted instead of, or blended with, Prescott's own $25,061 figure should treat that as a signal to ask for the correct, town-specific data before relying on the material further. The two-city comparison is worth including for context, exactly as it appears in this report, but only ever as a clearly separated, clearly labeled second line.
Reading the 30-Night Minimum Figure in Context
About a quarter of the Prescott sample, 25.0 percent of the roughly 801 listings, currently operates with a 30-night minimum stay requirement. On its own, this figure is easy to misread as evidence of strong extended-stay or remote-work demand in this market. It is more accurately read as a description of hosts' current settings than a description of guest demand, since the same extract shows the market's typical stay length running around 4.9 nights, well under the threshold that quarter of listings requires.
That gap between a widely adopted minimum-stay setting and the much shorter typical booking length suggests that a meaningful share of Prescott's listing stock may be filtering out more demand than it is capturing under that configuration, at least based on what this sample shows for the market overall. This is not a judgment on any individual host's strategy, since a specific property's own booking history could differ from the aggregate sample, but it is a pattern worth being aware of before assuming a 30-night minimum is the market norm simply because a quarter of listings have adopted it.
How This Report Should and Should Not Be Used
This kind of market report is most useful as a baseline check against claims, projections, or comps that a host, buyer, or reviewer encounters elsewhere. If a projection for a Prescott property assumes revenue meaningfully above $25,061 without a specific, property-level reason for that difference, this report is the reference point for asking why. If a comp set for a Prescott property draws on Phoenix figures, or blends the two cities' numbers into a single average, this report is the reference point for separating them back out.
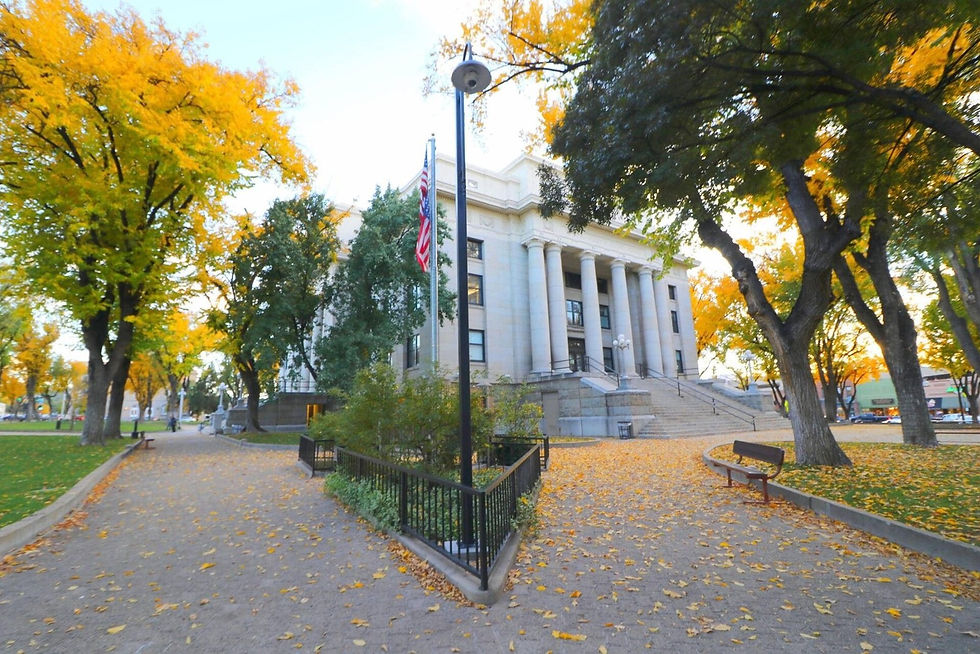
It is less useful, and should not be relied on, as a tool for predicting a specific property's future performance with precision. Aggregate figures describe a sample of 801 listings with real variation in size, location, condition, and management quality within that sample. A specific property could reasonably outperform or underperform the typical figure by a wide margin depending on factors this sample does not capture, including proximity to the courthouse square, property size and layout, photography and listing quality, and pricing strategy relative to comparable listings nearby.
The most defensible use of this report is as a sanity check: a way to confirm that a number being used elsewhere, in a listing description, a financing packet, a sales pitch, or a casual conversation about the market, is at least consistent with what the actual, current extract shows for this specific town, rather than a rounded-up guess, an outdated figure, or a number borrowed from a different market entirely.
What This Report Does Not Cover
This report describes market performance as captured by one data extract. It does not confirm registration or license status for any individual property, which must be checked directly at prescottaz.gov and kept current as fees, renewal windows, and remaining balances can shift within a calendar year. It does not account for individual property costs, financing terms, management fees, or any other expense that would convert a gross revenue figure into a net return. And it does not predict future performance beyond describing the most recent year-over-year trend the extract shows.
Anyone using this report as a starting point for a financing packet, a purchase decision, or a marketing strategy should treat it exactly as that: a starting point, grounded in one town's actual numbers, that still requires property-specific verification, current registration confirmation, and an honest accounting of costs before it becomes a complete picture of any individual Prescott short-term rental.
It is also worth noting what this report cannot tell you about the competitive landscape beyond the aggregate figures. It does not identify which specific listings are outperforming or underperforming the typical figure, what those top performers are doing differently, or how saturated any particular neighborhood or property type within Prescott has become relative to the market overall. A host looking for that level of granularity would need a property-specific competitive analysis, which is a different exercise than the market-wide baseline this report provides.
A Note on How Often This Data Should Be Rechecked
Because this report is built from a single extract covering a specific twelve-month window, its figures have a shelf life. Revenue, occupancy, and supply figures for a market this size can shift meaningfully within a year, particularly given the 16.1 percent supply growth already observed in the trailing period covered here. A host or buyer relying on this report six or twelve months from now should look for an updated extract rather than assuming these figures have held steady, especially given that the trend direction identified here, rising supply against declining revenue, is exactly the kind of pattern that can continue, plateau, or reverse depending on factors outside any single extract's visibility.
As a practical matter, treating any market report like this one as current for roughly a year, and then actively seeking a refreshed extract before it informs a major decision like a purchase, a refinance, or a significant repositioning of a listing, is a reasonable discipline. The alternative, carrying a data point forward indefinitely because it was accurate once, is exactly how blended, outdated, or borrowed figures end up in packets and pitches long after they stopped describing the market accurately.
Related Reading
More Prescott and high-desert host reading on desks, calendars, and listing clarity guests can trust.
Prescott, AZ Remote-Worker Stays: What the 30-Night Data Shows
Prescott, AZ Tourism Data: What Hosts Should Track, Not Confuse
Prescott vs Phoenix: Why Hosts Should Never Blend These Two Years
What It Actually Costs to Open a Prescott, AZ Short-Term Rental
Who Actually Books a Prescott Rental, and What They Came For
Buying a Prescott Short-Term Rental in 2026: What the Town's Own Numbe
The Prescott Visitor's Guide Independent Hosts Should Actually Write
Frequently Asked Questions
What did Prescott short-term rental listings earn on the current extract?
Typical listings in Prescott earned about $25,061 over the trailing year, based on a sample of 801 active rentals covering August 2025 through July 2026. This is a gross revenue figure describing the typical listing in the sample, not a projection for any specific property, and it does not account for individual costs like financing, management fees, or local taxes.
What are Prescott's ADR, occupancy, and RevPAR figures?
in this sample, Prescott's average daily rate is about $220, occupancy sits at 40.1 percent, and RevPAR comes in around $86. These figures work together to explain how the $25,061 typical annual revenue number is built, with RevPAR representing the most useful single figure for estimating per-night performance since it accounts for both rate and the share of nights actually booked.
Is the Prescott short-term rental market growing or shrinking?
On the current extract, revenue is down about 4.5 percent year over year while active supply is up about 16.1 percent over the same period. That combination suggests new listings have entered the market faster than trailing revenue has grown, putting downward pressure on average performance per listing even without a decline in overall market-wide demand.
How does Prescott compare to Phoenix on this same data?
Phoenix shows typical listings earning about $35,247 across roughly 5,820 active rentals on the same extract window, considerably larger than Prescott's 801-listing, $25,061 figure. The two markets differ structurally as well as in scale, with Phoenix drawing a larger, more urban, more year-round traveler base, while Prescott's guest is predominantly a short-trip highland visitor. The two figures should never be blended into one number for either market.
What kind of property does the Prescott data actually describe?
About 95.1 percent of the Prescott sample behind this sample is entire-home listings, meaning the reported figures are most representative of a whole-house short-term rental rather than a private room, shared space, or accessory unit. Anyone comping a different property type against this data should account for that mismatch rather than applying the whole-home figures directly.
Who is the typical guest booking a Prescott short-term rental?
The extract shows most guests arriving from Phoenix, then Tucson, for a planned highland stay of about 4.9 nights, booked roughly 44 days in advance. This points to a short, deliberate getaway rather than a long-stay or remote-work booking, even though about a quarter of listings in the sample currently set a 30-night minimum stay.
What does Prescott's seasonal calendar look like in this sample?
August is the clear peak month for revenue, with March and December functioning as genuine shoulder months that still carry meaningful income. February registers as the revenue hole, the weakest month for total revenue, while July registers separately as the occupancy hole, the month with the lowest share of booked nights, meaning the two soft stretches likely call for different diagnoses rather than one blanket seasonal discount.
Does this report confirm whether a specific Prescott property is licensed to operate?
No. This report describes market-wide performance data only. Remaining 2026 license status and remaining tax dollars for any specific property must be confirmed directly at prescottaz.gov, since a performance data extract has no way of verifying an individual property's current registration status, and that confirmation should be treated as current only as of the date it was checked.
Can this market report be used as the sole basis for a financing or purchase decision?
It should be treated as a starting point rather than a complete basis for any decision. This report describes gross revenue performance across a sample of listings; it does not account for a specific property's costs, financing terms, or management structure, and it does not confirm registration status. A complete evaluation needs this market data combined with property-specific verification and cost analysis.
Work with Crest & Cove Creative
Numbers only tell part of the story until a listing's photos and positioning actually reach the guest searching for this stay. Real revenue starts with getting found by the right traveler first.
Want to see how your Prescott listing's marketing stacks up against what this data shows guests are actually booking? Let's review the photos, description, and calendar strategy together and close the gap. Send the live listing draft and the facts you can actually cite.
Reach out at crestcove.co or (256) 998-7502.


Comments