
Coastal North Carolina STRs in 2026: An Operator's Field Report

Updated: Aug 27
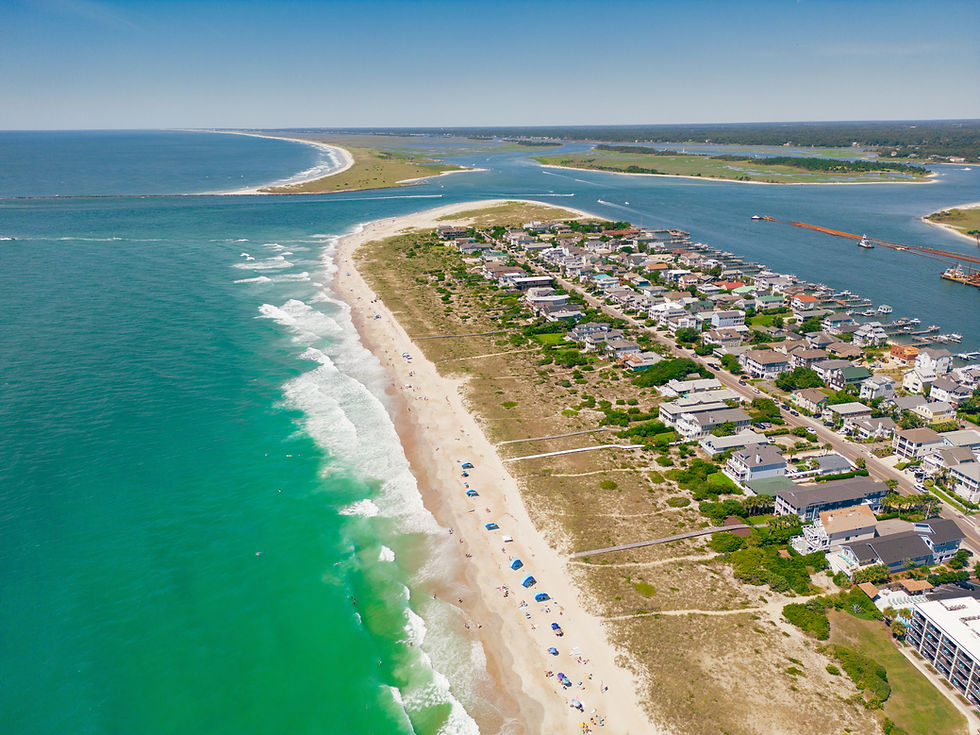
Coastal North Carolina is not one short-term rental market wearing five different beach towns as a costume. It is five counties with five different revenue lines, and an operator who blends them into a single "coastal NC is up" or "coastal NC is down" story is reading a number that does not exist anywhere in the actual county filings. This field report reads Dare, Carteret, Currituck, and Hyde on their own published figures, then says plainly where the same granularity is not yet available for Cape Fear and the Brunswick Islands.
None of this is legal, tax, or insurance advice, and none of the figures below are estimated or smoothed to fill a gap. Where a county has a published number, it is labeled by county and year. Where it does not, the section says so instead of borrowing a neighbor's trend line.
The point of separating these numbers is practical, not academic. A Dare County host pricing off a Carteret County growth rate, or a Cape Fear host assuming Corolla's 4x4-beach demand pattern, is underwriting a guest who was never actually going to book that house. This is not legal advice.
A Record Statewide Year That Still Splits Five Ways by County
North Carolina set a statewide record for visitor spending in 2024: $36.7 billion, up 3.1% from 2023, with 71 of the state's 100 counties posting gains. That headline is real, and it is also the exact number an operator should not apply to any single coastal county, because a record statewide total can sit on top of a county that had a down year.
Dare County is the case in point. Dare generated roughly $2.1 billion in total visitor spending in 2024 , the fourth-highest total of any North Carolina county, trailing only Mecklenburg ($6.4 billion), Wake ($3.5 billion), and Buncombe ($2.7 billion). That is an enormous number for a coastal county with no major city inside it, and it says something true about how much weight Dare carries in the state's tourism economy.
But total visitor spending and gross taxable accommodation revenue are two different lines on two different reports, and the second one is where Dare's 2024 story gets more complicated. The rest of this piece treats each county, and each of those two kinds of numbers, separately.
Dare County and the Outer Banks: A Record Year, Then a Real Pullback
Dare County's gross taxable accommodation revenue totaled $786.1 million in 2024. That is down 4.83% from 2023's record of $826.0 million , but it is still the third-highest year on record for the county. A host who only sees the year-over-year decline is missing that Dare just posted its third-best year ever, immediately behind an outlier record year.
The 2025 numbers available through the middle of the year add texture rather than alarm. Through July 2025, Dare's year-to-date gross occupancy revenue ran 1.14% ahead of the same period in 2024, and July 2025 alone produced $187.5 million in gross occupancy revenue, up 3.09% year over year. Full-year 2025 then finished essentially flat against 2024 , down 0.06% , while meals tax collections for the year were up 2.41%.
Read together, that is not a market in decline. It is a market that peaked in 2023, gave some of that back in 2024, and then held roughly level through 2025 while guests shifted a little more of their spending toward food. An Outer Banks host pricing 2026 off the 2023 peak is chasing a number the market has already told them it cannot sustain twice in a row; pricing off the 2025 flat line is pricing off what the market actually did.
Carteret County's Crystal Coast: Slower Growth, No Correction to Explain
Carteret County , the Crystal Coast , posted a 1.5% increase in visitor spending in 2024, reaching $743.4 million and ranking 11th among North Carolina counties statewide. That is a smaller county and a smaller number than Dare, and it is also a market that did not just come off a record year it had to give part of back.
The contrast matters for how a Crystal Coast listing should talk about its own trend. Dare's story right now is "still strong after a record, and roughly flat since." Carteret's story is "smaller, and still climbing." Those are not interchangeable narratives, and a Carteret host borrowing Dare's OBX-record-year framing is telling a guest, and a buyer underwriting the listing, a story that belongs to a different county's tax filing.
For an operator or an investor comparing the two, the honest read is that Carteret is the steadier of the two coastal peers on the numbers available here , not bigger, not more dramatic, just less exposed to the kind of single-year swing Dare just posted.
Currituck and Hyde: Two Small Counties Selling Two Different Trips
Currituck County , home to the Corolla and Carova 4x4 beaches , hit roughly $581 million in visitor spending in 2024, up 1.2% year over year. Hyde County, which contains Ocracoke, sat at roughly $61 million, down 0.8%. Both counties sit geographically next to Dare. Neither one is Dare, and neither one is interchangeable with the other.
Corolla and Carova are an access-controlled, 4x4-beach-driving trip , the demand there is built around a specific kind of vehicle-and-beach experience that a standard paved-road OBX listing does not replicate. Ocracoke is a ferry-access island, which means the trip itself starts with a ferry schedule, not a highway exit. A listing in either county that markets itself with generic "Outer Banks" language is skipping the one fact that actually decides whether a guest can get there on the day they wanted.
The dollar figures reinforce the point: Currituck grew, Hyde slipped slightly, and both moved independently of Dare's much larger swing. Three counties, three separate lines, sharing a coastline but not a market.
What the 2025-2026 Insurance Filing Actually Does to a Coastal Budget
This is not legal or insurance advice, and it does not tell any individual host what their premium will be , that depends on carrier, binder, and specific property. What can be stated as a dated fact is the North Carolina Rate Bureau's settled rate filing: increases of 7.5% effective June 1, 2025, and another 7.5% effective June 1, 2026, which compound to roughly 15.6% by the middle of 2026.
That filing applies statewide, which makes it one of the few numbers in this report that genuinely does apply across all five coastal sub-regions rather than to one county alone. A Dare host, a Carteret host, and a Cape Fear host are all budgeting against the same settled rate schedule, even though their revenue lines look nothing alike.
The practical move is to build the 2026 operating budget off the settled filing now rather than off last year's renewal invoice. A host who waits for the June 2026 renewal notice to find out what a 7.5% increase on top of a 7.5% increase actually costs in dollars is budgeting a quarter late.
Cape Fear and the Brunswick Islands: Where the County-Level Data Runs Thinner
Cape Fear , Wilmington, Wrightsville Beach, Carolina Beach, Kure Beach, and Topsail , and the Brunswick Islands in Brunswick County do not have the same year-over-year accommodation-revenue figures available in this pack that Dare, Carteret, Currituck, and Hyde do. That gap is stated here rather than filled with a borrowed number, because a Cape Fear listing quoting Dare's 4.83% or Carteret's 1.5% would be quoting a number that was never measured in Cape Fear.
What can be said honestly about the sub-region is geographic and competitive, not financial. Kure Beach is the quieter, family-residential southern neighbor in the Cape Fear cluster, anchored by Fort Fisher State Historic Site and the North Carolina Aquarium at Fort Fisher , a genuinely different guest than the weekend-visitor pattern that shapes Wrightsville Beach. And unlike Dare, where an established incumbent already dominates the professional-management channel, Wilmington and the Crystal Coast leave more daylight for an independent or boutique-portfolio operator to build market share without first having to dislodge that incumbent.
That is a real, usable fact for a Cape Fear host , it is just a different kind of fact than a percentage-growth figure. Until a sourced county-level accommodation number exists for Cape Fear or the Brunswick Islands, an honest listing or market page states the guest-type and competitive-landscape facts it actually has, instead of dressing the page in a neighboring county's growth rate.
Hotels vs. Vacation Rentals: Reading the Coastal Lodging Mix Honestly
The family-week-rental tradition that defines much of the Outer Banks in particular is not a marketing choice a host made up , it is how the listing stock itself was built, with large weekly-rental homes designed around Saturday-to-Saturday turnover, and it is how the guest base on that stretch of coast actually books. That structural fact shapes how an OBX listing competes with hotels differently than it would in a market built around nightly hotel rooms.
A hotel guest is comparing nightly rates and amenities. A weekly-rental guest on the Outer Banks is comparing houses, bedroom counts, and proximity to the beach access their extended family already knows , a different buying decision entirely, and one that a listing description written like a hotel amenities page does not actually speak to.
That distinction travels differently across the five sub-regions in this report. It applies most directly where the weekly-rental tradition is strongest; it applies less directly in a market like Wilmington, where a mix of shorter urban stays and beach-week rentals already coexist. A host's copy should reflect which of those two patterns their specific listing and county actually sit inside.
What Coastal NC Hosts Should Actually Plan Around Through 2027
Read your own county's number, not a blended coastal average that does not exist in any filing. Dare's 2025 flat line, Carteret's steady 1.5% climb, Currituck's 1.2% gain, and Hyde's 0.8% dip are four separate stories, and a listing description or investor memo that averages them into one "coastal NC growth rate" is reporting a figure nobody actually published.
Price 2026 against the trend the market has actually shown, not against a single outlier peak. On the Outer Banks specifically, that means pricing off the 2025 flat baseline rather than the 2023 record the market has already failed to repeat once.
Budget insurance off the settled statewide filing , 7.5% in June 2025, another 7.5% in June 2026 , now, not at renewal. And if your listing sits in Cape Fear or the Brunswick Islands, where the county-level accommodation data is not yet published in this pack, build your marketing and underwriting language around the guest-type and competitive facts that are actually known, rather than borrowing a growth number that belongs to a different county's books.
Related Reading
More independent-host reading on listing copy, calendars, and operable decisions guests can trust.
Frequently Asked Questions
Is Dare County's 2024 accommodation-revenue decline a sign the Outer Banks market is shrinking?
No. Dare's $786.1 million in gross taxable accommodation revenue for 2024 was down 4.83% from 2023, but 2023 was itself a record year at $826.0 million, and 2024 still ranks as the third-highest year on record for the county. A single-year pullback immediately after a record is reversion, not a shrinking market — and 2025 data through the full year came in essentially flat against 2024, which supports a leveling-off read rather than a decline.
How does Carteret County's Crystal Coast growth rate compare to Dare County's numbers?
Carteret grew 1.5% to $743.4 million in visitor spending in 2024, ranking 11th statewide, while Dare's narrower accommodation-tax line fell 4.83% off a record year. The two counties are not directly comparable in scale, but the underwriting takeaway is that Carteret did not have a peak year to correct from — it is a smaller market posting steady, uninterrupted growth rather than a market absorbing a post-record pullback.
What actually separates Corolla in Currituck County from Ocracoke in Hyde County as rental markets?
Access. Corolla and the Carova 4x4 beaches require a specific vehicle-and-beach driving trip that a paved-road listing elsewhere on the Outer Banks does not replicate, while Ocracoke is reachable only by ferry, which means the trip itself starts on a ferry schedule rather than a highway exit. Currituck's visitor spending rose 1.2% in 2024 to roughly $581 million; Hyde's slipped 0.8% to roughly $61 million — two small counties moving independently of each other and of Dare.
How much will coastal North Carolina property insurance actually rise by mid-2026?
Two back-to-back 7.5% increases, one landing June 1, 2025 and the second landing June 1, 2026, stack to roughly a 15.6% total move over that window rather than a simple 15%, because the second increase applies on top of the first. This is a statewide rate-bureau filing, not a quote for any specific property, and it is not insurance or legal advice — an individual host's actual premium still depends on carrier, binder, and location, and should be confirmed with a licensed agent.
Why did North Carolina set a statewide visitor-spending record in 2024 while Dare County's accommodation revenue fell?
Those are two different measurements. The $36.7 billion statewide record, up 3.1%, reflects total visitor spending across all 100 counties, 71 of which posted gains. Dare's $786.1 million figure is narrower — gross taxable accommodation revenue specifically — and it fell only relative to 2023's own record year. Dare's total visitor spending, at roughly $2.1 billion, still ranked fourth-highest of any county in the state in 2024.
What happened to Dare County's occupancy revenue and meals tax collections through 2025?
Dare's mid-year pace was ahead of the prior year by a little over one percentage point, and the single month of July did better than that, up over three percent year over year. By December the annual total had settled back to almost exactly flat against 2024 -- a fractional dip, not a decline -- while the county's meals tax line grew faster than its occupancy line did, which points to guests spending a bit more per trip on food even as room-night revenue held roughly steady.
Should a Wilmington or Cape Fear host expect the same growth trend as Dare or Carteret County?
There is no published county-level accommodation-revenue figure for Cape Fear or the Brunswick Islands in the data behind this report, so no, a host there should not import Dare's or Carteret's percentage. What is known is structural: Wilmington and the Crystal Coast do not have the kind of dominant incumbent management company that Dare does, which leaves more room for an independent or boutique operator to build share on service and listing quality rather than competing against an entrenched brand.
Is the family week-rental tradition on the Outer Banks a marketing advantage or a disadvantage?
It is neither by default — it is a structural fact a listing either uses correctly or ignores. Large weekly-rental homes built around Saturday-to-Saturday turnover compete against hotels on a completely different axis than nightly rates: bedroom count, proximity to a specific beach access, and space for an extended family. A listing written like a hotel amenities page is answering a question that weekly-rental guests on the Outer Banks were never asking.
Who should confirm tax, insurance, and county-specific figures before a host finalizes a 2026 budget?
A licensed insurance agent for premium specifics, a qualified accountant or tax professional for occupancy and accommodation-tax obligations by county, and the relevant county tax office for the current published year of any accommodation-revenue figure being used. This report compiles dated, sourced figures for planning context; it is not legal, tax, or insurance advice, and county figures should be reverified before they are used in a listing, a lender package, or a public marketing claim.
What is the single biggest planning mistake a coastal North Carolina host could make heading into 2026?
Treating the coast as one market. Dare, Carteret, Currituck, and Hyde each posted a different trend in 2024 and into 2025, and Cape Fear and the Brunswick Islands don't yet have the same granular figures published at all. A host, agency, or buyer who blends those five stories into a single "coastal NC" growth or decline number is underwriting off a figure that no county actually filed.
Work with Crest & Cove Creative
Five coastal North Carolina counties posted five different 2024 numbers, and none of them add up to one honest "coastal NC" trend line. Reading them separately is the only version of this report an operator can actually underwrite against.
Work with Crest & Cove Creative to turn your own county's published numbers into listing copy and investor materials that hold up under a direct question. Start at crestcove.co/audit or call (256) 998-7502 to have your Dare, Carteret, Currituck, Hyde, Cape Fear, or Brunswick Islands listing checked against the actual filing behind it.
Reach out at crestcove.co or (256) 998-7502.


Comments